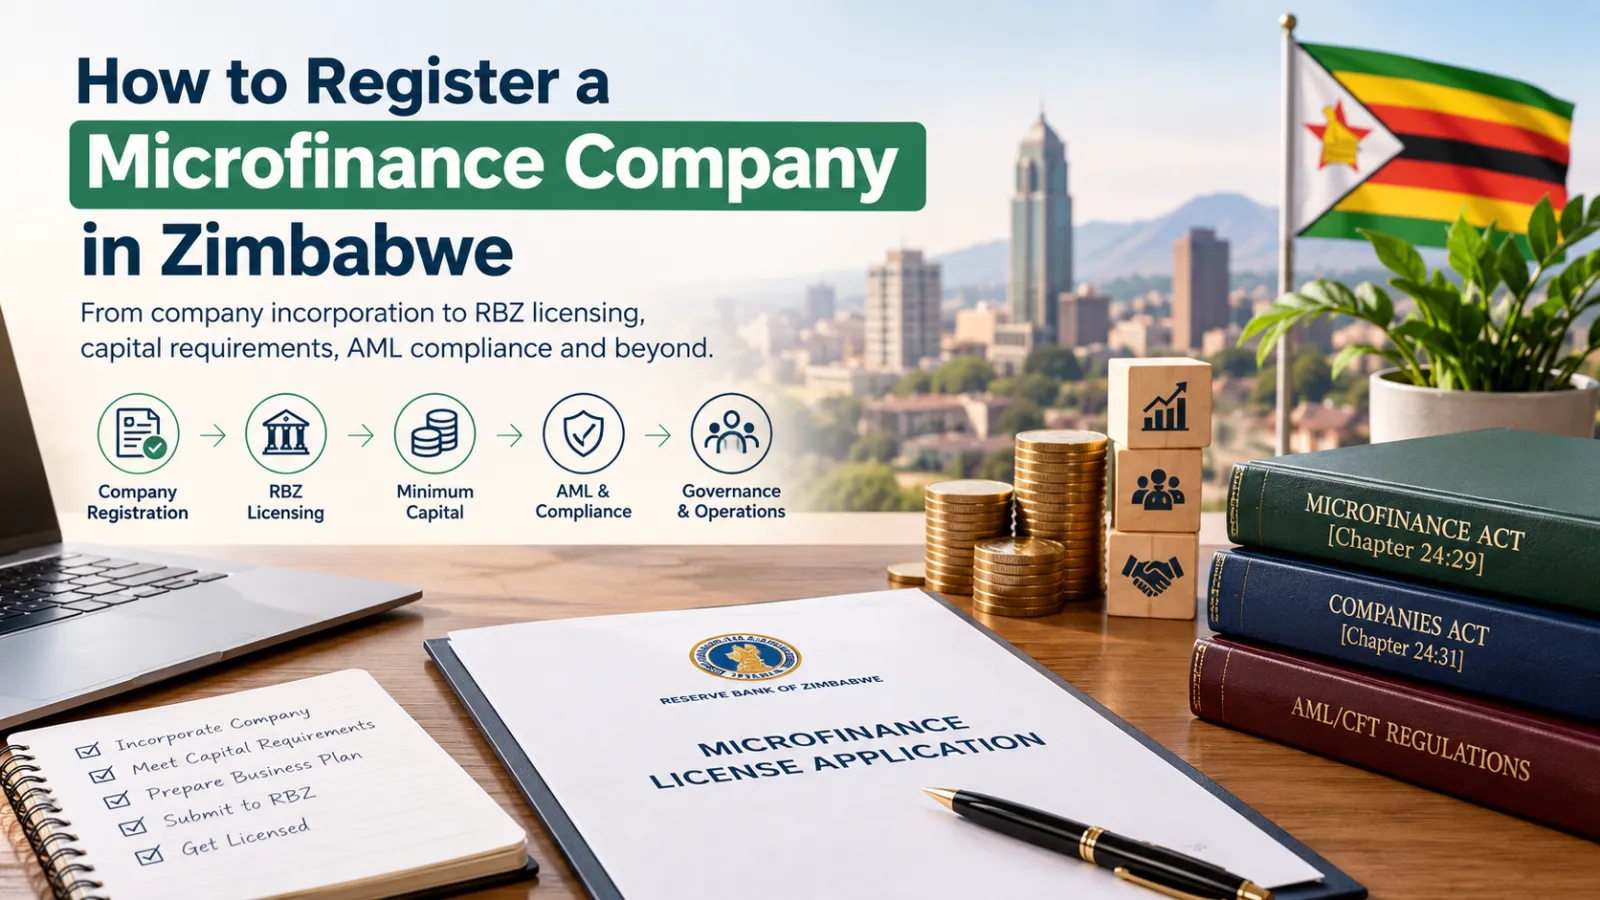
Starting a microfinance business in Zimbabwe is more than registering a company and opening an office.
If a business intends to provide loans as a microfinance institution, it enters a regulated financial-services industry supervised by the Reserve Bank of Zimbabwe (RBZ). The legal framework requires the business to first exist as a properly incorporated company and then obtain registration as a microfinance institution before conducting microfinance business.
This distinction is important. A company registration certificate does not by itself give a business permission to operate as a microfinance institution.
The main legislation governing the sector is the Microfinance Act [Chapter 24:29], while company formation is governed by the Companies and Other Business Entities Act [Chapter 24:31].
1. First decide what type of microfinance institution you want to operate
Zimbabwe's Microfinance Act recognises two main types of microfinance business:
Credit-only microfinance institutions
Deposit-taking microfinance institutions
A credit-only MFI primarily provides loans or other credit facilities.
A deposit-taking MFI accepts deposits and conducts lending activities. This is a substantially more demanding regulatory category.
The distinction matters because the capital requirements, governance requirements and regulatory obligations are significantly different.
The RBZ currently lists separate licensing requirements and application forms for both categories.
For a new entrepreneur intending to lend their own or shareholders' funds, the credit-only MFI route is generally the relevant starting point. A business should not accept deposits from the public simply because it has been incorporated as a company.
2. Incorporate the company first
Before applying to the RBZ, the applicant must be a company.
Section 6 of the Microfinance Act states that:
"No person shall conduct any microfinance business unless he or she is registered"
and also provides that a person cannot be registered as a microfinance institution unless that person is a company.
The company itself is incorporated under the Companies and Other Business Entities Act [Chapter 24:31].
That Act recognises private limited companies, public companies and other forms of business entities. It also provides for electronic or manual registration of constitutive documents and issuance of a certificate of incorporation.
For a typical privately owned microfinance business, the practical structure is therefore:
Founders → Private Limited Company → RBZ Microfinance Registration → Licensed Microfinance Operations
The company's constitutional documents should also reflect the intended lending business. RBZ's credit-only MFI requirements specifically call for certified copies of the Certificate of Incorporation and Memorandum and Articles of Association with lending included as one of the company's objects.
This is one reason it is better to plan the company structure around the intended regulated activity from the beginning rather than incorporating an unrelated company and trying to change everything later.
3. Have the required share capital
Capital is one of the first things the RBZ will examine.
For credit-only microfinance institutions, the current minimum capital requirement is the Zimbabwe-dollar equivalent of US$25,000.
The RBZ's 2024 Monetary Policy Statement explicitly lists:
"Credit Only Microfinance Institutions — Minimum Capital US$25,000"
as the minimum capital requirement.
The RBZ's 2024 microfinance industry report also confirms that credit-only MFIs were required to maintain the equivalent of US$25,000 in minimum capital.
This is worth highlighting because older documents available online can contain historical figures. For example, an older RBZ licensing document refers to US$20,000 increasing to US$50,000 by 2020. That document is historical and should not be confused with the current prudential requirement.
The current RBZ publications are the better reference point for the applicable capital requirement.
For deposit-taking microfinance institutions, the requirement is dramatically higher: the current minimum capital is the equivalent of US$5 million.
Therefore, someone planning a small lending business should carefully distinguish between:
TypeMinimum capitalCredit-only MFIUS$25,000 equivalentDeposit-taking MFIUS$5 million equivalent
The figures are regulatory capital requirements and should not be interpreted as the total amount required to successfully operate the business. A new MFI will also need working capital for salaries, premises, technology, compliance, loan administration, legal costs, auditing and other operating expenses.
4. Be prepared to prove where the money came from
The RBZ does not simply want to know how much money the shareholders have invested.
It also wants to know where that money came from.
The RBZ's credit-only MFI requirements state that shareholders must disclose the source of capital resources invested in the microfinance business. Shareholders must also satisfy fitness, probity and good-standing requirements.
For individual shareholders holding at least 5%, the RBZ requirements include documents such as:
Net worth statements
National identity documents
Police clearance
Tax clearance
Affidavits concerning insolvency and civil/criminal judgments
Corporate shareholders holding at least 5% have additional requirements, including audited financial statements, incorporation documents, ownership information and tax clearance.
Where ownership involves companies or other legal entities, the RBZ also requires disclosure of the ultimate beneficial owners.
This means that simply putting money into a company's bank account is not enough. The regulator needs to be satisfied that the institution's ownership and capital are transparent and legitimate.
5. Establish a proper board and management structure
A microfinance company is not expected to operate like an informal lending operation.
The Microfinance Act requires the operations of a microfinance institution to be directed by a board.
Following the 2019 amendments, the Act provides for a minimum of:
3 directors for a credit-only MFI
5 directors for a deposit-taking MFI
The board is responsible for formulating policies and supervising the institution's microfinance business.
The RBZ also assesses the qualifications, experience and fitness of directors and senior management.
For example, the RBZ licensing requirements state that the CEO of a credit-only MFI must be a full-time employee, while directors and senior management must have appropriate qualifications and relevant professional experience.
The application therefore needs to demonstrate that the proposed institution has people capable of actually running a regulated financial business.
6. Prepare a serious business plan
The business plan is one of the most important parts of the application.
This is not simply a document explaining that the company wants to give people loans.
The RBZ requires information covering areas such as:
Business identity
The application should identify the proposed institution, its location and its branches.
Market analysis
The business plan should explain:
Who the institution intends to serve
The characteristics of that market
Expected market changes
Factors affecting the market
The developmental value of the institution
Business strategy
The applicant needs to explain the products and services it intends to offer and how it expects to achieve its objectives.
Financial projections
The RBZ requires financial projections, including:
Projected balance sheets
Projected income statements
Projected cash-flow statements
Financial assumptions
The assumptions should address issues such as inflation, market interest rates, lending rates, bad debts and economic growth.
In other words, the regulator wants to see that the proposed MFI has a credible business model rather than simply a desire to lend money.
7. Create proper lending and credit policies
A microfinance company needs documented procedures for how it will lend money.
The RBZ requires applicants to provide credit or operational policy and procedure manuals.
These policies should address matters such as:
Loan application procedures
Credit assessment
Approval limits
Loan sizes
Loan tenure
Interest rates
Fees and charges
Collections
Default management
Complaints
Client protection
Risk management
The RBZ's licensing requirements specifically require information on minimum and maximum loan sizes, maximum loan maturity periods and a breakdown and justification of charges.
This is an important distinction between a regulated MFI and an informal money lender.
The regulator wants the institution to have a repeatable and controlled process for making credit decisions.
8. Prepare a compliant loan agreement
Before the institution starts lending, it needs a proper loan agreement.
The Microfinance Amendment Act requires agreements entered into by a microfinance institution to be in writing and clearly set out their material terms and conditions.
The legislation also provides for prepayment rights and requires applicable penalties for prepayment to be specified.
Importantly, a clause allowing the MFI to unilaterally change the interest rate, repayment period or another borrower obligation is void.
The RBZ licensing requirements therefore ask applicants to submit a copy of the loan agreement they intend to use.
A loan agreement should therefore not be treated as a document to create after licensing. It should form part of the institution's regulatory preparation.
9. Put a complaints system in place
Customer complaints are also part of the regulatory framework.
The RBZ requires a comprehensive complaints procedure manual.
Once licensed, the procedure must be visible to clients, and complaints must be recorded in a complaints register with the resolution process documented.
This reflects a broader principle in Zimbabwe's financial-services regulation: borrowers are customers of a regulated financial institution and cannot simply be treated as debtors with no consumer protections.
The RBZ's Consumer Hub specifically provides information on loan agreements, over-indebtedness, dispute resolution and consumer protection.
10. Meet AML and customer identification requirements
Microfinance is also subject to Zimbabwe's anti-money-laundering framework.
The RBZ's 2025 AML/CFT/CPF Guideline specifically states that banks and microfinance institutions are exposed to heightened money-laundering, terrorist-financing and proliferation-financing risks.
The guideline states that, effective 1 January 2023, the Reserve Bank's Bank Supervision, Surveillance and Financial Stability Division was appointed as the competent supervisory authority for AML/CFT/CPF supervision of banks and microfinance institutions.
The underlying Money Laundering and Proceeds of Crime Act establishes requirements around customer identification and verification, beneficial ownership and suspicious transactions.
Consequently, a new MFI needs an AML/CFT compliance framework rather than simply collecting a borrower's name and phone number.
A practical compliance framework will normally need to address:
Customer identification
Customer verification
Beneficial ownership
Politically exposed persons
Risk assessment
Record keeping
Suspicious transaction reporting
Internal controls
AML compliance responsibilities
The exact implementation should be designed against the applicable legislation and current RBZ/FIU requirements.
11. Register the company with ZIMRA
Company registration and RBZ registration do not replace tax registration.
ZIMRA states that companies and other businesses engaging in business are required to register with ZIMRA and comply with their applicable tax obligations.
ZIMRA's current guidance says businesses can register through the TaRMS Self Service Portal and receive a Taxpayer Identification Number (TIN).
The RBZ's own MFI licensing requirements also require a tax clearance certificate for the applicant company and relevant shareholder/director documentation.
Therefore, tax compliance needs to be addressed as part of preparing the regulatory application rather than treated as an unrelated administrative task.
12. Secure proper business premises
A microfinance company needs formal business premises.
The RBZ's credit-only MFI requirements state that microfinance companies must operate from formal business premises and may not operate from premises that are also used for residential purposes.
Lease agreements for the head office and branches must be submitted.
This is another indication that the RBZ licensing process is designed around an actual operating institution rather than a company that exists only on paper.
13. Consider data protection requirements
Microfinance institutions handle significant quantities of personal information.
A typical loan application may contain:
National identification information
Addresses
Employment information
Income information
Bank details
Credit information
Contact details
Information about guarantors
Information relating to directors or beneficial owners
Zimbabwe's Cyber and Data Protection framework therefore becomes relevant.
POTRAZ's data protection regulations establish requirements concerning data controllers, including obligations relating to processing activities, international transfers and certain categories of personal information.
A microfinance company should therefore assess its data-controller obligations and ensure that its loan-management software, customer records, cloud infrastructure and third-party service providers are compliant with Zimbabwe's data protection requirements.
14. Submit the application to the Reserve Bank of Zimbabwe
Once the company, capital, governance structure, management, business plan, policies, premises and supporting documentation are ready, the applicant can submit the MFI application to the RBZ.
The RBZ provides a specific Application for Registration as a Microfinance Institution in Zimbabwe.
The application form states that completed applications and proof of payment of the applicable fees are submitted to the Director of the Bank Supervision Division at the Reserve Bank of Zimbabwe.
The Microfinance Act also specifies what the application must contain, including information about:
Directors
CEO
Chief accounting officer
Shareholders holding at least 5%
Authorised and paid-up share capital
Certificate of incorporation
Memorandum and Articles
Business plan
Prescribed fee
Additional information required by the Registrar
The Registrar then assesses whether the applicant has sufficient capital, an appropriate business plan, fit-and-proper directors and qualified management and whether the institution will conduct business prudently.
15. The RBZ does not automatically approve every application
Meeting the paperwork requirements does not guarantee registration.
The Microfinance Act gives the Registrar discretion to refuse an application where the statutory requirements are not satisfied or where registration would not be in the public interest.
However, the Act provides procedural protections. Before refusing an application, the Registrar must notify the applicant of the proposed refusal and reasons and give the applicant at least 30 days to make representations.
The Act also provides that the period between receipt of a complete application and notification of the Registrar's decision should not exceed 60 days, unless the applicant consents to an extension.
This means applicants should think of the process as a regulatory assessment rather than a simple registration fee followed by automatic approval.
16. Registration is only the beginning
Once registered, the MFI enters an ongoing regulatory relationship with the RBZ.
The RBZ maintains a public register of microfinance institutions, identifying whether an institution is registered as a credit-only or deposit-taking MFI.
The Reserve Bank continues to supervise the sector.
In fact, the RBZ published a list of registered microfinance institutions covering January to June 2026, demonstrating that registration status is actively maintained and publicly monitored.
The RBZ's Bank Supervision function includes ongoing supervision, surveillance and examinations of regulated financial institutions.
Therefore, obtaining the certificate is not the end of compliance. It is the point at which ongoing regulatory obligations begin.
Credit-only MFI vs Deposit-taking MFI
For someone considering entering Zimbabwe's microfinance sector, the difference between the two models is substantial.
RequirementCredit-only MFIDeposit-taking MFIMain activityLendingDeposit-taking and lendingMinimum capitalUS$25,000 equivalentUS$5 million equivalentMinimum board under amended Act3 directors5 directorsAccept deposits from publicNoYes, subject to regulationRBZ registrationRequiredRequiredBusiness planRequiredRequiredFit and proper assessmentRequiredRequiredAML/CFT complianceRequiredRequiredConsumer protectionRequiredRequiredOngoing RBZ supervisionYesYes
The capital figures are based on the RBZ's current published minimum capital requirements.
A practical registration roadmap
For an entrepreneur starting from zero, the process can be viewed as follows:
Step 1: Decide whether the business will be credit-only or deposit-taking.
Step 2: Incorporate the company under the Companies and Other Business Entities Act.
Step 3: Make sure lending/microfinance is properly reflected in the company's objects.
Step 4: Structure the shareholders and disclose beneficial ownership.
Step 5: Inject and document the required capital.
Step 6: Obtain the required tax registrations and clearances.
Step 7: Establish the board and appoint qualified management.
Step 8: Secure compliant business premises.
Step 9: Prepare the business plan and financial projections.
Step 10: Prepare credit, operational, risk and AML/CFT policies.
Step 11: Prepare the loan agreement and complaints-handling procedure.
Step 12: Establish customer identification, verification and record-keeping processes.
Step 13: Assess data protection obligations.
Step 14: Complete the RBZ MFI application and pay the applicable application fee.
Step 15: Submit the application and supporting documents to the RBZ Bank Supervision Division.
Step 16: Respond to any regulatory queries or requests for additional information.
Step 17: Obtain the RBZ registration certificate before conducting regulated microfinance business.
The most important point
The biggest mistake a new entrepreneur can make is to think:
"I have registered my company, so I can start giving loans."
That is not how Zimbabwe's microfinance regulatory framework works.
The company registration creates the legal entity. The RBZ microfinance registration authorises the entity to conduct the regulated microfinance business.
The Microfinance Act is explicit that a person may not conduct microfinance business unless registered. It also provides serious consequences for unregistered microfinance activity.
For anyone planning to enter the industry, the sensible approach is therefore to design the company, capital structure, governance, lending policies, technology and compliance framework around the RBZ requirements from the beginning.
Microfinance is a business, but it is also a regulated financial activity. The difference matters.
Official sources and further reading
The Reserve Bank of Zimbabwe provides the principal regulatory material for prospective MFIs, including application forms and minimum licensing requirements.
The Microfinance Act [Chapter 24:29] establishes the legal framework for registration, supervision and regulation of microfinance business in Zimbabwe.
The Companies and Other Business Entities Act [Chapter 24:31] governs the incorporation and administration of companies in Zimbabwe.
ZIMRA provides guidance on registration and tax obligations for new businesses.
The RBZ's 2025 AML/CFT/CPF Guideline provides the regulatory framework for anti-money-laundering and counter-terrorist-financing compliance by banks and microfinance institutions.
Important: Regulatory requirements can change through Acts, regulations, RBZ circulars, prudential standards and monetary-policy statements. Anyone preparing an actual MFI application should verify the latest RBZ requirements directly before submitting an application.