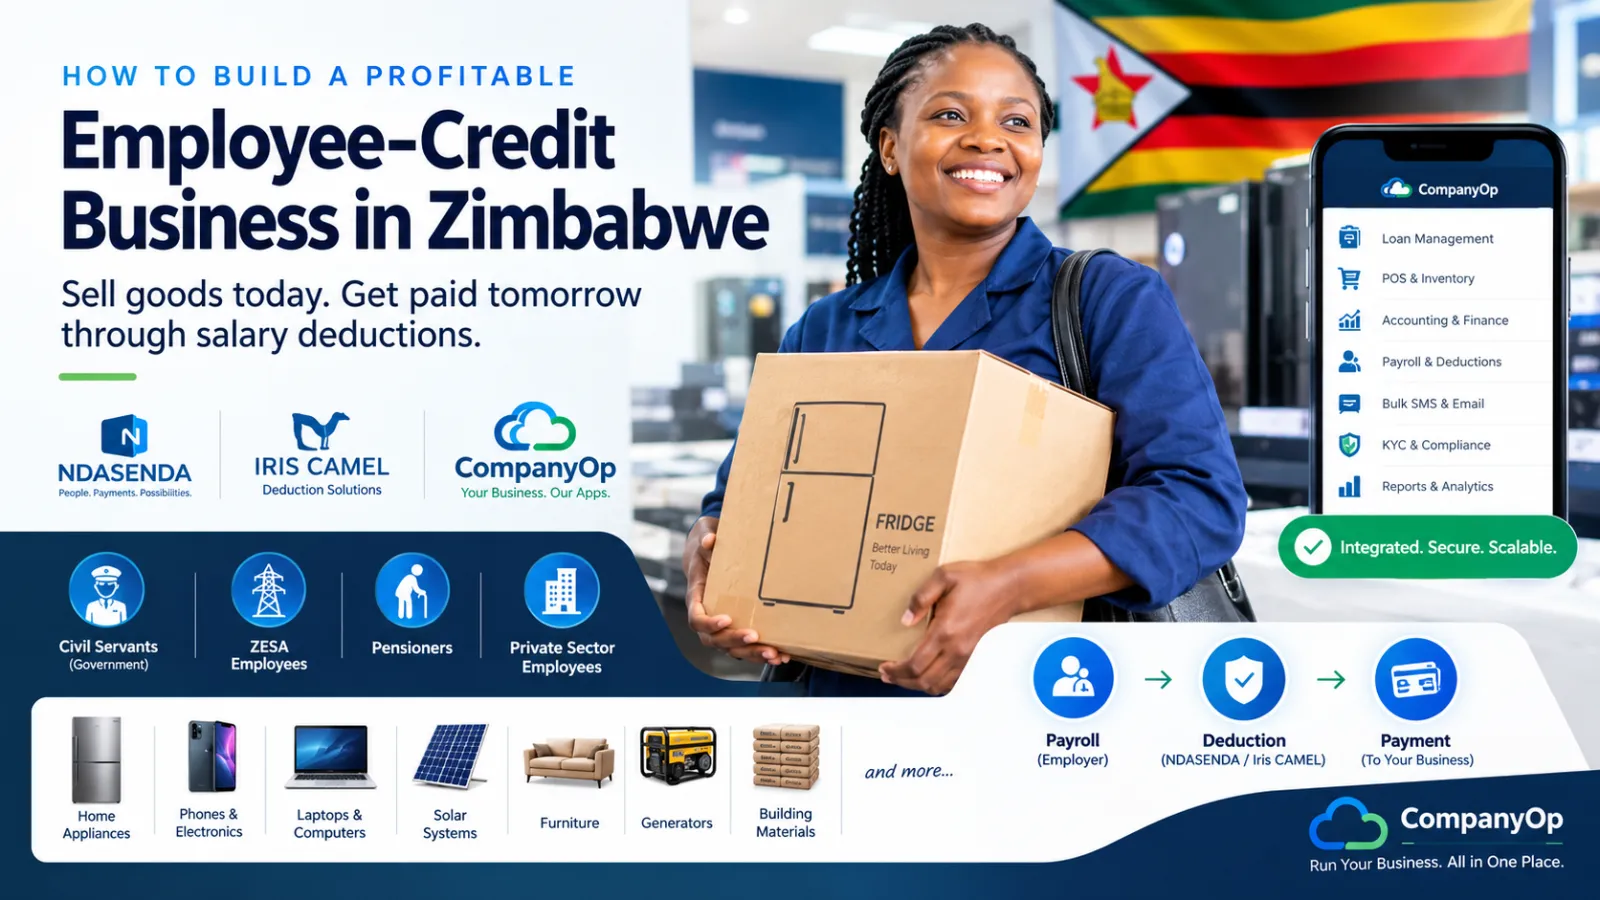
There is a powerful business model that many Zimbabwean businesses can use but few execute properly:
Sell a product to an employed customer today, allow them to pay over time, and collect the agreed instalments through a formal salary-deduction or stop-order arrangement.
The customer gets the product without paying the full amount upfront.
The business gets access to a predictable repayment mechanism.
And, if structured correctly, the business can build a recurring customer base around employees of government departments, pension organisations and private companies.
This model can work for furniture, phones, laptops, appliances, solar equipment, building materials, funeral products, insurance, school-related products and other goods or services.
But there is an important distinction:
You cannot simply decide to deduct money from someone's salary.
The deduction mechanism must be authorised and supported by the relevant employer/payroll or deduction platform. Zimbabwe's Public Service Commission confirms that its Salary Services Bureau manages salary payments and deductions, while existing providers such as NDASENDA and Iris CAMEL provide infrastructure for submitting deduction instructions.
This article explains how the model works, how to build the business around it, what existing platforms are doing, and how CompanyOp can become the operating system behind the business.
1. The Basic Business Model
Imagine you sell refrigerators.
A customer wants a refrigerator worth US$600.
Instead of telling them:
"Come back when you have US$600."
you can structure a payment plan.
For example:
ItemAmountCash price$600Deposit$100Balance$500Repayment period10 monthsMonthly instalment$50
The customer takes the refrigerator today.
They then repay the agreed amount each month.
If the customer's employer and the applicable deduction arrangement support it, the repayment can be collected through a salary deduction/stop-order mechanism.
This changes the sales conversation completely.
You are no longer only selling:
"A $600 refrigerator."
You are selling:
"A refrigerator that you can take home today and pay for from your salary over time."
That can dramatically increase the number of people who can afford your products.
2. Why Employees Are an Attractive Customer Segment
An employee with a regular salary has something that a completely informal customer may not have:
predictable income.
That does not mean the customer is automatically creditworthy.
It means there is a potentially predictable source of repayment.
Zimbabwe already has established financial products built around this principle. For example, First Capital Bank's civil-servant lending information says an agreement between the bank and employer is required for deduction at source before the loan can be assessed.
Existing businesses have also built product-financing models around salary deductions.
For example, Mutsai Marketplace advertises electronics, appliances, furniture and other products financed through salary deductions and says it works with financial institutions for its financing arrangements.
That tells you something important:
The opportunity is not theoretical.
The model already exists in Zimbabwe.
The opportunity is to execute it better in a particular market or product category.
3. Don't Start by Buying Stock
This is where many entrepreneurs get the model wrong.
They think:
"I need to buy 500 phones and then find people to sell them to."
No.
Start with the repayment channel and customer base.
A better sequence is:
Employer/employee market → financing arrangement → customer applications → credit approval → supplier/product → delivery → repayment
rather than:
Buy stock → hope people buy → struggle to collect money.
Your first question should therefore be:
Who are my customers and how will repayments be collected?
4. Pick One Employee Market First
Do not start with:
"We sell to everyone."
That makes marketing much harder.
Choose one segment.
For example:
Government employees
Teachers, nurses, police officers, administrators and other civil servants.
The Public Service Commission's Salary Services Bureau is responsible for salary payments and the collection/remittance of deductions within the government payroll system.
Pension-related customers
There is also infrastructure around the Public Service Commission's pension administration, and existing systems such as Iris CAMEL specifically support deductions involving pension services.
ZESA employees
This is another potential employer market, but do not assume that because an organisation has salaried employees you can automatically submit deductions to its payroll.
You need to establish the employer's actual deduction policy, approval process, payroll contact and any required agreement.
Private-sector employees
This may actually be the most interesting market for a new business.
Factories, schools, hospitals, security companies, large retailers, mining companies, banks and other employers can potentially become customer acquisition channels.
NDASENDA, for example, explicitly markets its corporate deduction platform to private-sector employers and says deductions can be established with employee consent through accounts or HR offices.
5. The Most Important Part: Get the Deduction Arrangement Right
This is where the business becomes serious.
You should never build the model around:
"The employee promised to pay me from their salary."
You need an actual collection mechanism.
There are several possibilities:
Option A: Government salary deduction
You establish the required relationship/approval to submit deductions through the relevant government payroll infrastructure.
Option B: Pension deduction
Where applicable, you work through the relevant pension administration/deduction infrastructure.
Option C: Private employer deduction
You establish an agreement with the employer and its payroll/HR department.
Option D: Financial institution partnership
You partner with a licensed financial institution that provides the financing while you supply the goods.
This can be particularly useful if your business model is closer to buy-now-pay-later/product finance than ordinary retail.
6. Understand the Regulatory Boundary
This part is critical.
If your business is simply selling goods on credit, you need proper legal advice on how the arrangement should be structured.
If you are actually operating a credit-only microfinance business, Zimbabwe's Reserve Bank of Zimbabwe states that a person cannot conduct credit-only microfinance business without a valid credit-only microfinance licence under the Microfinance Act.
So don't casually launch a website saying:
"We are a microfinance institution and give loans to civil servants."
without first establishing the applicable licensing requirements.
There is a potentially different structure where:
You sell the product → a licensed financial institution finances the purchase → the customer repays the financier → you receive payment for the product.
That structure can be commercially attractive, but it needs to be properly documented.
Get Zimbabwean legal/accounting advice before launching the credit product.
7. Existing Platforms Show That the Model Works
There are already companies operating in this space.
NDASENDA
NDASENDA is one of the clearest examples.
Its corporate deduction platform describes deductions at source for private-sector employees and says employee consent is used to establish deductions.
NDASENDA also describes its history with Zimbabwe's Salary Services Bureau. According to its own published history, it rolled out a salary-deduction platform for the government's payroll department in 2016 and subsequently expanded to other government payroll institutions.
Its NDASENDA PAY product is designed around lenders, merchants, employers and employees and includes employer, merchant, financier and employee portals.
That is essentially the ecosystem you are trying to understand:
Employee + Employer + Merchant + Financier + Payroll deduction.
8. Iris CAMEL
Another important Zimbabwean example is Iris CAMEL.
Iris CAMEL describes itself as a platform for submitting deductions to the Public Service Commission's Salary Services Bureau and Pension Services Bureau.
According to QATCTECH, it can be used by companies that sell products or services to civil servants and government retirees, including insurance companies, banks and other businesses.
It is offered in three forms:
Stand-alone deduction submission system
Integration with Iris LAPP
REST API for connecting another system
That third option is particularly important from a software perspective.
It means the deduction system does not necessarily have to be the system running your entire business.
Your business software can manage customers, products, sales, loans and repayments while the deduction platform handles the submission side.
QATCTECH also states that Iris LAPP integrates directly with Iris CAMEL, allowing deductions to flow from the loan-management system into the deduction platform.
9. This Is Where CompanyOp Fits
The mistake would be to think:
"CompanyOp needs to become another Iris CAMEL."
It doesn't.
CompanyOp should be the business operating system around the deduction business.
CompanyOp already follows a modular model where businesses can select the applications they actually need and operate them inside one company workspace.
The relevant applications are particularly interesting for this business model.
CompanyOp currently offers:
Loan Management
Point of Sale & Inventory
Accounting & Finance
Payroll Management
Bulk SMS & Email
Client Background Checks
Contracts Management
Leads Management
PDF Signer
among other applications.
That creates a much bigger proposition than simply:
"Software for salary deductions."
10. The Full CompanyOp Workflow
Imagine you start a business called SmartHome Credit.
You sell:
refrigerators
televisions
smartphones
laptops
solar systems
furniture
generators
appliances
You target employed customers.
Your workflow could look like this:
Step 1 — Find an employer market
For example:
Civil servants.
Or:
ZESA employees.
Or:
Employees of private companies.
You establish the appropriate deduction arrangement first.
Step 2 — Advertise products
You advertise:
"Get a refrigerator today. Pay monthly."
Instead of advertising only the cash price, show:
Cash: $600
From: $60/month
subject to eligibility and approved terms.
Step 3 — Customer applies
The customer provides:
name
national ID
employer
employee number
salary information
contact details
address
product requested
repayment period
supporting documents
The application enters your CompanyOp Loan Management workflow.
Step 4 — Verify the customer
You check:
identity
employment
income
existing obligations
affordability
credit history where applicable
outstanding balances
required employer information
CompanyOp's Client Background Checks application is designed around KYC/CDD, sanctions, PEP and watchlist screening.
That becomes particularly useful when your operation grows.
11. Don't Give Everyone the Same Credit Limit
This is where you start thinking like a financial business rather than a retailer.
Suppose two employees earn:
Employee A: $350/month
Employee B: $2,000/month
You should not automatically give both a $1,000 product loan.
Build a credit policy.
For example:
FactorConsiderationSalaryHigher stable income may support greater affordabilityEmployment lengthLonger employment may reduce some risksExisting deductionsImportantCurrent obligationsImportantProduct valueDetermines exposureRepayment periodLonger period changes riskPrevious repayment historyExtremely importantEmployerRelevant to your agreement and payroll mechanism
The exact limits should be determined by your credit policy and applicable law.
12. Approve the Product
Once approved:
Customer → Credit approved → Product reserved
The system should record:
principal/product value
deposit
fees where legally permitted
repayment amount
repayment frequency
number of instalments
first deduction date
final deduction date
deduction reference
employer
employee number
This becomes the customer's repayment schedule.
13. Deliver the Product
Now the customer receives the product.
Your POS/Inventory system records:
Product leaves inventory.
The loan system records:
Customer owes X.
Accounting records:
The financial transaction.
This is exactly where having separate disconnected systems becomes painful.
With an integrated ERP, the same customer and transaction can be connected across the relevant applications.
14. Submit the Deduction
The deduction instruction is then sent through the applicable deduction mechanism.
This is where CompanyOp would need an integration with the relevant deduction provider or employer payroll system.
Conceptually:
CompanyOp
↓
Approved repayment
↓
Deduction integration/API
↓
Employer / SSB / relevant payroll organisation
↓
Salary processed
↓
Deduction collected
↓
Payment reconciliation
The important point is that CompanyOp should not claim to directly control SSB, PSB or ZESA payroll systems unless an actual integration/agreement exists.
Instead, CompanyOp can become the system managing everything around the deduction.
15. Reconcile Every Payment
This is where many small businesses fall apart.
They sell the products.
They create spreadsheets.
Customers pay.
Then nobody knows exactly who has paid what.
Your system should show:
CustomerProductInstalmentPaidBalanceCustomer AFridge$60$60$240Customer BLaptop$75$75$450Customer CSolar$100$0$800
You should be able to identify:
Expected this month
versus
Actually received this month.
16. Handle Failed Deductions Immediately
Never assume:
"The deduction system will pay us forever."
People:
resign
retire
transfer
change employers
go on unpaid leave
change payroll details
reach retirement
have deductions rejected
have insufficient allowable deduction capacity
Your system needs exception management.
For example:
Deduction failed
→ SMS customer
→ create follow-up task
→ determine reason
→ resubmit if appropriate
→ switch to alternative payment method if necessary
→ escalate overdue account
This is where CompanyOp's messaging functionality becomes useful.
17. Use Bulk SMS to Run the Portfolio
Imagine you have 3,000 customers.
You don't want employees manually calling everyone.
You want automated communications such as:
Your monthly instalment of $75 is scheduled for deduction this month. Your outstanding balance is $450.
Or:
Your latest repayment has been received. Your remaining balance is $375.
Or:
Your salary deduction was not received this month. Please contact our accounts department.
CompanyOp's Bulk SMS & Email application is available as an integrated application and is listed as free with Loan Management.
18. Accounting Becomes Extremely Important
Once you have hundreds or thousands of customers, you are no longer running a normal shop.
You have:
Inventory + Receivables + Repayments + Revenue + Cash Flow.
Your accounting system needs to answer:
How much did we sell?
How much is outstanding?
How much cash should we receive?
How much was actually received?
How much inventory remains?
How much capital is tied up in receivables?
How much is overdue?
What are our monthly expenses?
What is our actual profit?
CompanyOp's Accounting & Finance application provides the accounting layer around the other applications.
19. The Real Business Is Not Selling Products
This is the most important lesson.
Suppose you sell 100 refrigerators.
That's good.
But suppose you have:
100 customers × $50/month
That's:
$5,000/month of scheduled repayments.
Now imagine:
1,000 customers × $50/month
That's:
$50,000/month of scheduled repayments.
The business becomes interesting because you have built a portfolio of customers paying over time.
That recurring repayment book can become an extremely valuable business asset, provided the underlying agreements, financing structure, collections and regulatory requirements are sound.
20. But Don't Confuse Revenue With Cash
This is another major trap.
If you sell:
$100,000 worth of products on credit
you have not necessarily received $100,000 in cash.
You may have:
$100,000 receivables.
Your business still needs working capital.
If you need to buy stock from suppliers before customers finish paying you, you can run out of cash even while your accounting system shows strong sales.
This is why successful product-finance businesses carefully manage:
working capital + repayment duration + default rate + inventory turnover.
21. Start With Products People Actually Need
Don't begin by financing random luxury products.
Start with products that have strong demand.
For example:
Electronics
smartphones
laptops
televisions
Household
refrigerators
washing machines
stoves
beds
furniture
Power
solar systems
batteries
inverters
backup power
Education
laptops
tablets
educational equipment
Building
roofing materials
cement
doors
windows
other building materials
The product should ideally have:
high demand + reasonable resale value + manageable ticket size.
22. Use Employer Groups as Distribution Channels
This is where the model becomes much more powerful.
Instead of trying to acquire customers individually, create an employer programme.
For example:
CompanyOp Employee Purchase Programme
Then approach an organisation.
You can say:
"We provide employees with access to approved products on structured payment plans, subject to eligibility and the employer's approved deduction process."
Now the employer becomes a distribution channel.
Instead of finding one customer at a time, you potentially get access to hundreds or thousands of employees.
23. Don't Assume ZESA or Any Employer Will Accept You
This deserves its own section.
You mentioned ZESA.
The opportunity may be real, but the correct process is not:
"ZESA employees have salaries, therefore we can deduct from them."
The correct process is:
Identify the responsible employer/payroll department.
Establish whether third-party deductions are permitted.
Identify the required application/vendor process.
Determine whether there is an approved deduction/stop-order mechanism.
Obtain the required agreement.
Determine employee-consent requirements.
Determine deduction limits and priority rules.
Determine submission format/API/process.
Establish reconciliation procedures.
Only then launch the product.
The same principle applies to other employers.
24. The Employee Should Understand What They Are Signing
Never hide the repayment arrangement.
The customer should clearly understand:
cash price
financed price, where applicable
deposit
instalment
number of instalments
total amount payable
repayment dates
applicable interest/charges
consequences of default
deduction authorisation
cancellation/return conditions
what happens when employment ends
Transparency protects both sides.
25. Don't Build the Business Around a Spreadsheet
A spreadsheet might work for:
20 customers.
It becomes dangerous at:
500 customers.
At 5,000 customers it becomes a serious operational problem.
You need a proper system that connects:
Customer
↓
Application
↓
Credit decision
↓
Product
↓
Inventory
↓
Agreement
↓
Repayment schedule
↓
Deduction
↓
Payment
↓
Accounting
↓
Customer communication
↓
Collections
That is an ERP problem.
And that is precisely where CompanyOp fits.
26. The CompanyOp Stack for This Business
A strong implementation could look like this:
Core
CompanyOp Loan Management
Manage:
applications
borrowers
approval workflows
repayment schedules
outstanding balances
portfolio
collections
CompanyOp currently lists Loan Management at a US$25 once-off licence fee plus US$2 per loan per month.
Sales
CompanyOp POS & Inventory
Manage:
products
stock
sales
customers
deliveries
Finance
CompanyOp Accounting & Finance
Manage:
receivables
payments
expenses
journals
financial reporting
Communication
CompanyOp Bulk SMS & Email
Manage:
payment reminders
approval notifications
failed deduction notifications
statements
marketing
Compliance
CompanyOp Client Background Checks
Manage:
KYC
sanctions
PEP screening
watchlists
investigations
Documents
CompanyOp PDF Signer
Manage signed agreements and supporting documentation.
The advantage is that these aren't five unrelated systems.
They operate within the same CompanyOp workspace. CompanyOp's stated model is to allow businesses to add applications as their needs grow while maintaining a shared company workspace, users and permissions.
27. CompanyOp + Deduction Platform
This is the bigger opportunity.
CompanyOp does not need to replace NDASENDA or Iris CAMEL.
It can sit alongside the deduction infrastructure.
For example:
                    CUSTOMER
                       |
                       v
                COMPANYOP PORTAL
                       |
              +--------+--------+
              |                 |
              v                 v
       LOAN MANAGEMENT    POS & INVENTORY
              |                 |
              |                 v
              |              PRODUCT
              |              DELIVERY
              |
              v
       REPAYMENT SCHEDULE
              |
              v
       DEDUCTION INTEGRATION
              |
       +------+-------+
       |              |
       v              v
      SSB        PRIVATE EMPLOYER
       |              |
       +------+-------+
              |
              v
        PAYMENT RECEIVED
              |
              v
         ACCOUNTING
              |
              v
        CUSTOMER BALANCE
This is a much stronger proposition than simply selling another loan-management system.
28. The Sales Pitch Changes
Instead of telling a business:
"CompanyOp has loan management software."
say:
"Sell products on structured payment plans, manage your customers, stock, repayments and accounts in one system."
And for a merchant:
"Turn your retail business into a structured employee-finance business."
And for a microfinance company:
"Manage the entire loan lifecycle from application to repayment and accounting."
And for a product supplier:
"Give your customers a way to buy today and pay over time while keeping your portfolio under control."
That is much more compelling.
29. The Best Way to Start
If I were building this business from scratch, I would not start with ten employers.
I'd start with:
One product category
For example:
solar systems
One employee segment
For example:
a single large employer
One financing structure
For example:
12-month repayment
One collection mechanism
approved salary deduction/stop order
One software platform
CompanyOp
Then measure:
applications
approval rate
average product value
average deposit
average monthly repayment
deduction success rate
default rate
customer acquisition cost
gross margin
cash conversion
outstanding portfolio
If the model works with 100 customers, scale it to 500.
Then 1,000.
Then approach another employer.
30. The Real Competitive Advantage
The software is important.
But the software alone isn't the moat.
The real moat becomes:
Employer relationships + customer database + repayment history + supplier relationships + financing relationships + operational infrastructure.
Imagine that after three years you have:
10,000 customers
across:
15 employers
with:
$2 million in outstanding receivables
and years of repayment history.
That is a very different business from a normal furniture shop.
You have built an employee-commerce and financing network.
31. Where CompanyOp Can Take This
The long-term vision could be bigger than simply selling CompanyOp licences.
CompanyOp could eventually provide the technology layer for businesses running:
Employee Purchase Programmes
Employees browse products.
Credit Applications
They apply for financing.
Automated Credit Decisions
The merchant evaluates affordability and eligibility.
Product Fulfilment
Approved products are issued.
Salary Deduction
Repayments are submitted through the appropriate deduction channel.
Portfolio Management
The merchant sees the entire book.
Accounting
Payments automatically flow into the financial records.
Collections
Failed deductions trigger follow-up workflows.
Reporting
Management sees the performance of every employer, branch, product and loan.
That is a serious vertical.
32. One Important Lesson From NDASENDA and Iris CAMEL
NDASENDA and Iris CAMEL demonstrate something important:
the deduction infrastructure itself is valuable.
NDASENDA has built around deduction processing and expanded into an ecosystem connecting employees, employers, merchants and financiers.
Iris CAMEL focuses heavily on the deduction-submission layer and provides integration options for other systems.
CompanyOp can approach the problem from the opposite direction:
Don't become just the pipe carrying the deduction. Become the system running the business that generates the deduction.
That's the opportunity.
33. The Final Business Formula
The model can ultimately be reduced to this:
Find employees with reliable income
↓
Give them access to useful products
↓
Structure affordable payment plans
↓
Perform proper credit and affordability checks
↓
Obtain the required employee consent
↓
Use an authorised deduction/collection mechanism
↓
Deliver the product
↓
Track every instalment
↓
Reconcile every payment
↓
Follow up failed deductions
↓
Build repayment history
↓
Increase the customer base
↓
Add more employers
↓
Add more products
↓
Scale the portfolio
And the technology underneath it can be:
CompanyOp Loan Management + POS & Inventory + Accounting + Messaging + Compliance, connected to the appropriate salary-deduction infrastructure.
The opportunity for Zimbabwean businesses
The biggest mistake would be to look at this as simply:
"How do I sell a fridge to a civil servant?"
The better question is:
"How do I build a repeatable employee-commerce business where customers can acquire useful products and repay through a properly authorised payroll deduction mechanism?"
That is a much bigger business.
Zimbabwe already has evidence of the infrastructure required for this model. The Public Service Commission operates payroll and deduction functions; NDASENDA operates deduction infrastructure; Iris CAMEL provides deduction submission technology; and businesses are already marketing products financed through salary deductions.
CompanyOp's role is to bring the merchant's side of the operation together.
Instead of running your business across a POS, spreadsheet, loan book, accounting package, SMS system and document folders, you can build the operation around one connected workspace.
Sell the product. Manage the customer. Track the repayment. Control the stock. Reconcile the money. Run the business from one system.